Connecticut’s wind history
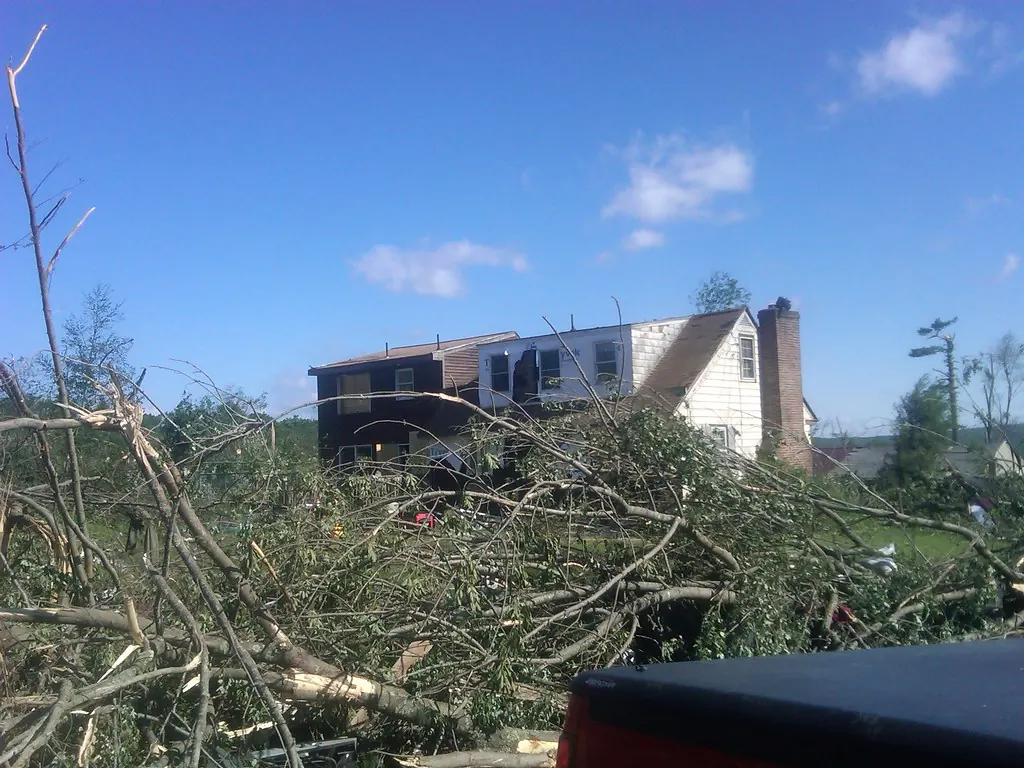
Connecticut sees tornadoes less often than the Midwest, but it has had serious ones. The October 1979 tornado that struck Windsor Locks and the July 1989 tornado that hit Hamden and parts of New Haven were among the strongest in the region’s modern record. On May 15, 2018, several tornadoes and a macroburst crossed New Haven and Fairfield counties in a single afternoon. Add winter nor’easters and summer straight-line winds, and wind is one of the most common sources of claims in the state.
Wind damage that gets missed
- Lifted shingles that resealed. Shingles that lifted and laid back down may have broken seals and creased mats that will fail in the next storm.
- Siding and trim. Vinyl siding cracks and unlocks; matching replacement panels are often discontinued.
- Racked framing. Doors that stick or new drywall cracks after a storm can point to structural movement.
- Fences, sheds and outbuildings. Other-structures coverage is easy to overlook in a large claim.
- Interior water. Wind-driven rain through damaged openings can affect insulation and finishes far from the visible damage.
Percentage deductibles
Some Connecticut policies carry a separate percentage deductible for windstorm or hurricane losses. Whether it applies depends on the trigger language in your policy, often tied to an official hurricane warning or a named storm. Our hurricane deductible calculator shows what a percentage means in dollars.
Frequently asked questions
Does it matter whether it was a tornado or straight-line wind?
Usually not for coverage, since both are windstorm under most policies. It can matter for which deductible applies, so check your trigger language.
What evidence helps a wind claim?
Dated photos, National Weather Service storm reports for your area, debris patterns and an inspection soon after the event all help show what the wind did.
My adjuster says the damage is wear and tear. Can appraisal fix that?
Appraisal values covered damage. If the carrier says the damage is not covered at all, that is a coverage dispute, which may need an attorney rather than appraisal.