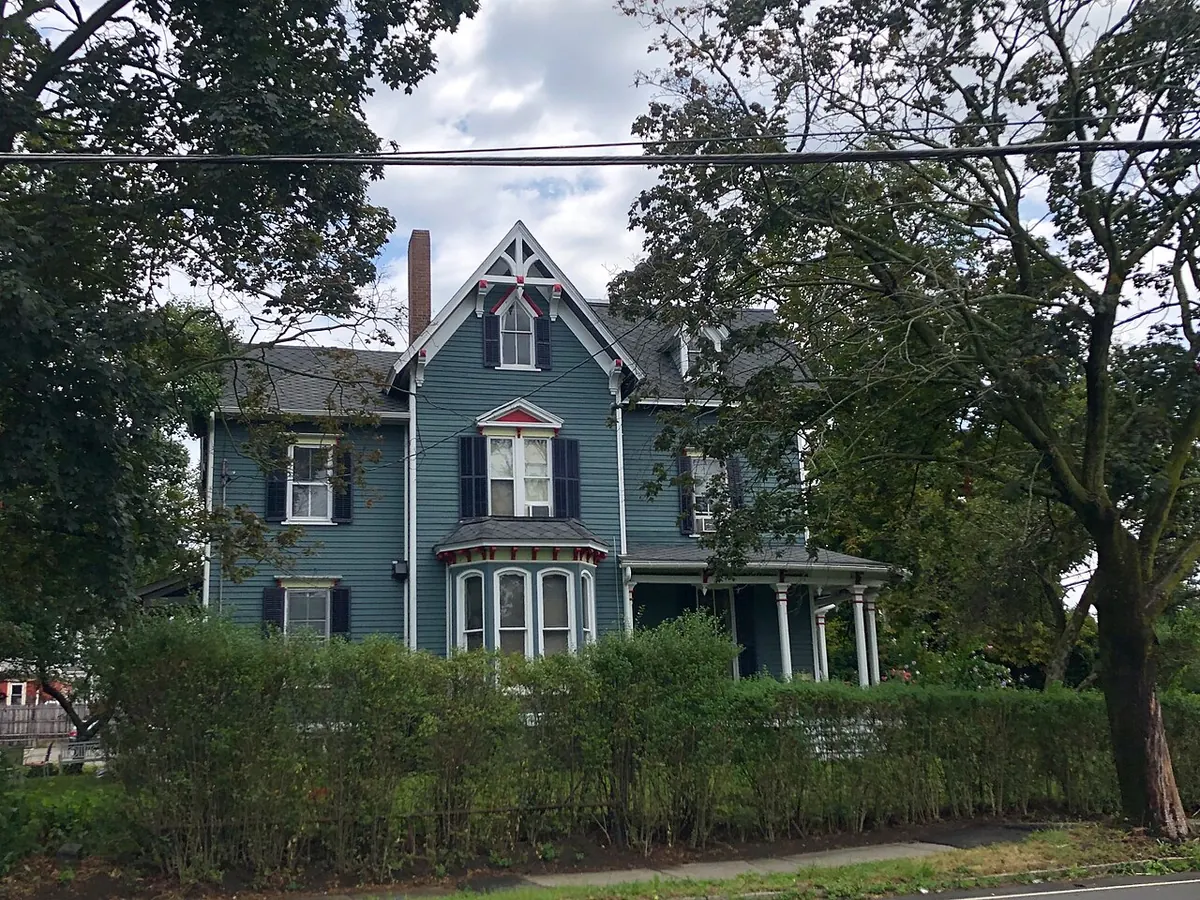
Why Connecticut homes are easy to underprice
A large share of Connecticut’s housing was built before 1960. That means plaster walls, old-growth trim, slate and wood shingle roofs, balloon framing and additions from several decades stacked on one house. A desk estimate built from standard line items tends to miss those details.
- Plaster versus drywall. Replacing a damaged plaster wall with drywall can leave a visible mismatch and a thickness difference at every transition.
- Trim and millwork. Profiles that are no longer stocked must be milled, which costs far more than off-the-shelf trim.
- Multifamily layouts. Hartford, New Britain, Waterbury and Bridgeport have thousands of two- and three-family houses where one leak can affect three units, three kitchens and a shared stairwell.
- Uniform appearance. Siding and roofing that cannot be matched raise questions about how far repairs must extend.
What a homeowners appraisal looks like
- A free call to understand the loss, the carrier’s position and your deadlines.
- A document review: declarations page, the carrier’s full estimate, photos and any contractor bids.
- An on-site inspection with measurements, moisture readings where relevant, and detailed photos.
- An independent estimate you can read, with each difference from the carrier’s number explained.
- Appraisal, if it fits, with us serving as your named appraiser.
Condo unit owners
If you own a condo, your HO-6 policy and the association’s master policy split responsibility according to the declaration and bylaws. Before we value anything, we sort out which items belong to the unit and which belong to the association, so the right policy is asked to pay.
Frequently asked questions
Do you handle two- and three-family houses?
Yes. Multifamily homes are common across Connecticut’s cities, and we scope each unit and the common areas separately so nothing is missed.
Will appraisal raise my premium?
Appraisal is a policy condition, not a new claim. Premiums depend on many factors and your insurer’s rating practices; we cannot predict renewal pricing.
Should I wait to repair until appraisal is done?
Make reasonable temporary repairs right away to prevent more damage and keep receipts. For permanent repairs, document everything carefully first, because the panel may need to see conditions.